You worked every hour of it. So where did the money go?
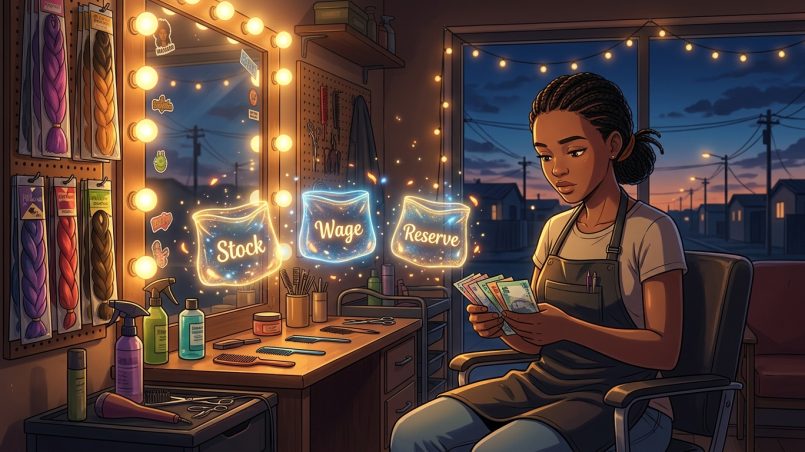
It’s Saturday at 6pm. The chair has been full since eight this morning.
You count the cash. It’s a good number. Better than last week.
By Tuesday it’s gone, and you couldn’t say where if someone asked you.
I’ve watched a friend of mine live this. He’s a spray painter, and he earns good money.
By the weekend it’s gone, and he can’t account for it.
Groceries. Petrol for the car. Electricity. Then the money is up.
Nothing on that list is reckless. Every item is real, and that’s what makes it so hard to see.
The petrol might even be for work. Nobody can tell, because it all came out of the same pocket.
You do the maths in your head, the way you always do. Stock, transport, data, the loan to your cousin, and the groceries.
It never adds up to the number you counted on Saturday.
The customers came. The orders came. The money didn’t stay.
Nobody says this part out loud: being busy and being paid are two different things.
I call the setup behind it ‘The Three Pockets‘, and most hustles are running on only one.
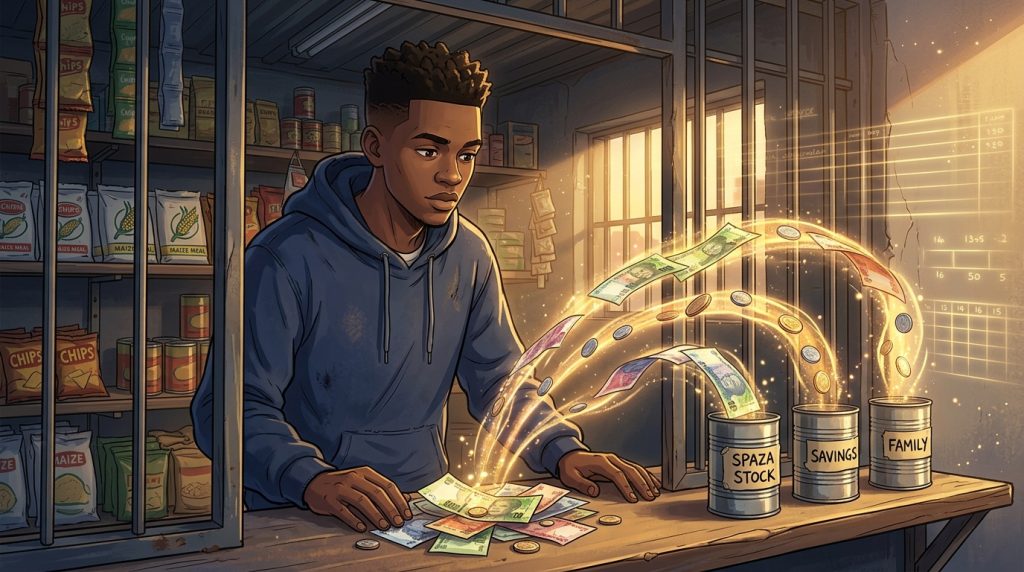
The Three Pockets: Where Every Rand Belongs
Phase 1 gave you names for what you inherited. The Rule, the Reaction, the Receipt. The Mirror. The Silent Contract. The Sprint, the Freeze, the Hide.
Phase 2 is Money in Motion. It starts with the money that moves through your hands every day, not only on payday.
Most hustles run on one pocket. Everything goes in. Everything comes out. Nobody keeps score.
The Rule underneath it is old: if the money is in my hand, it’s mine to spend. The Receipt is that empty Tuesday.
A business runs on three pockets.
1. The Stock Pocket
Stock is money that belongs to the business, not to you.
The next batch of hair. The vetkoek flour and oil. Airtime and data to resell. Petrol or taxi fare to the supplier. The electricity that keeps the stall lit.
You don’t spend from this pocket. You only move it, and it comes back with more in it.
2. The Wage Pocket
The Wage is what you pay yourself. A fixed amount, on a fixed day.
You choose the number before the week starts, and closing time doesn’t get a vote.
Your family ceiling from Week 3 lives inside this pocket. The giving gets decided here, in advance, instead of at the till.
3. The Reserve Pocket
The Reserve covers the days that go wrong.
The stage-4 night when the dryers stop. The freezer that defrosts while you sleep. The client who pays next month. The pair of clippers breaks on a Saturday.
A hustle takes those hits from your own groceries. A business takes them from the Reserve.
What You Actually Made
Here is the number most hustlers have never calculated. These rands are an example, so swap in yours.
| Example week | Rand |
|---|---|
| Cash counted on Saturday | R3,000 |
| Stock you had to replace | R1,800 |
| Transport and data | R200 |
| What you actually made | R1,000 |
Most hustlers call the R3,000 “what I made”.
You made R1,000. The other R2,000 was never yours to spend. It only passed through.
The One-Pocket Hustle vs the Three-Pocket Business
| One-Pocket Hustle | Three-Pocket Business | |
|---|---|---|
| Where the money goes | One pocket, one mood | Stock, Wage, Reserve |
| What you know | “It was a good week” | A number, in a book |
| Who gets paid first? | Whoever asks first | The Stock, then your Wage |
| A slow week feels like | Panic, borrowing, skipping meals | A dip the Reserve already planned for |
| “I’ll pay you Friday.” | Said to anyone, remembered by nobody | One written rule |
| What the Tuesday looks like | Empty | Same as Monday |
| What grows | Your hours | Your income |
The Name You Give It
Call it a hustle, and you behave like someone surviving the week.
Call it a business, and you behave like someone planning the next one.
Self-image drives behaviour. Behaviour creates evidence. The evidence is your Tuesday.
Why This Hits Harder in South Africa
Most of our money is cash, and cash is visible.
Everybody on the street can see the line outside your stall. Nobody can see the stock bill behind it.
So the family sees R3,000 and assumes R3,000. That’s where the first request comes from, before you’ve restocked.
Then there’s the tab. The neighbour who needs bread until month end. The aunty who takes the chicken pieces and says she’ll sort you Friday.
It’s Ubuntu, and it feels wrong to refuse. But a tab with no limit and no record is a loan you made without ever deciding to lend.
Then the power goes. Stage 4 doesn’t care what’s in your Reserve. If you’ve got no Reserve, load-shedding takes the money out of your own pocket.
Add a bank that doesn’t recognise what you do, and the shortcuts begin. Everything lands on one phone, one account, one card.
Here is how it looks across the people we serve:
- The floor worker with a Saturday stall, selling to the same people they work next to.
- The graduate reselling sneakers or airtime off WhatsApp, with every sale landing in a personal account.
- The hairdresser, barber, or car-wash owner whose daily cash and daily needs sit in the same tin.
- The tradesman — spray painter, welder, plumber — paid in lumps per job, with paint, petrol and personal bills all drawn from one balance.
- The professional running a side business after hours, and paying for it from the salary.
Cape Flats, township, suburb. The name changes. Hustle, side-line, “my thing.” The one-pocket habit does not check your postcode.
And nobody taught you this at home. Most of our parents survived on cash they never had the luxury to split. They did the best they could with one pocket.
The Move: Give Your Hustle a Payslip
Do this over seven days. A notebook is enough.
- Count for seven days. Write every rand that comes in and every rand that goes out, including the “small” ones. Do it at close, every day, before you do anything else.
- Find your real number. Take the week’s cash in. Subtract everything that went back into the business. What’s left is what you actually made.
- Open the three pockets. Three envelopes, three tins, or an account and two pockets inside it. Label them Stock, Wage, Reserve. The money gets split at close, not at month end.
- Fill Stock first. Replace what you used before anything else moves. If Stock is short, the Wage waits.
- Set your Wage. Pick one amount for yourself, paid on the same day every week. Take your Week 3 family ceiling out of it, not out of the Stock.
- Write one rule for credit. Who gets it, how much, and by when. Put it somewhere you can see it. “I’ll pay you Friday” becomes a rule instead of a mood.
- Review every Sunday. Ten minutes. Three totals. Did the Wage get paid? Is the Reserve growing, even by R20?
If step 2 hurts, that tells you how long the money has been invisible.
The Part Nobody Wants to Hear
A boring Wage beats a big week.
The big week is the dangerous one. It teaches you the wrong Rule: that money comes in waves, so spend it like a wave.
Pay yourself the same amount on a great week and a slow week. The great week fills Stock and Reserve. The slow week gets paid from the Reserve.
That is the whole difference between a hustle and a business. A hustle swings with the week. A business smooths it.
This is the boring season of consistency. Nobody claps for it, and it’s the season that builds the thing.
This reaches past money. A person who keeps a promise to a notebook every Sunday builds self-trust, and that carries into everything else you run.
FAQs
What is the difference between a hustle and a business?
A business knows its numbers and pays its owner a set amount. A hustle runs on whatever is in the pocket today. You can be small and still be a business.
How do I know if I’m making a profit?
Take what came in and subtract what you spent to earn it, such as stock, transport, data, and electricity. What remains is your profit. If you’ve never done this sum, start with Step 1 of The Move.
Do I need a separate bank account?
You don’t need one to start. Three envelopes work on day one. A separate account or savings pocket helps once the money is moving, because a physical split is harder to spend by accident.
Do I need to register my business?
You can start earning without it. As you grow, registration and tax rules may apply to you, so check the current requirements on the SARS and CIPC websites.
How much should I pay myself?
Start with an amount you can pay every week, even on a slow one. Work it out from your seven-day count, and raise it only when the Reserve has a cushion.
What if my family treats my business cash like their cash?
Move the cash into the pockets at close, so it’s already labelled by the time anyone asks. Then answer from the Wage, using the ceiling you set in Week 3. The number is already decided.
How do I handle customers who owe me?
Write every debt in the book, with a name and a date. Decide your credit rule before the next person asks. A written rule is easier to say than a mood.
Is selling on credit to neighbours wrong?
No. But a tab with no limit costs you stock you can’t replace. Give yourself a ceiling for credit, the same way you gave your family one.
How do I handle load-shedding hitting my income?
Plan for it as a cost. Build the Reserve first so a blackout doesn’t come out of your groceries, and look at what you can sell or prepare that doesn’t need power.
How do I stop spending my stock money?
Make the stock money hard to reach. A sealed envelope, a separate account, or a different bag. The harder it is to touch, the longer it lasts.
What if I sell only in cash and keep no records?
Start with a notebook and a pen. Write down the day’s cash in and out at close. Records can be rough and still tell you the truth.
Can I do this while I have a full-time job?
Yes. Your salary is one stream and the hustle is another. Keep them in separate pockets so the salary stops paying for the side business by accident.
Should I put all my profit back into the business?
No. Pay your Wage first, then fill the Reserve, then reinvest what’s left. A business owner who is broke and burnt out can’t run the stall.
What if my numbers show I’m making a loss?
That’s useful information, not a verdict. It tells you whether to change the price, the supplier, or the product. You can’t fix a number you’ve never seen.
How long before I see a difference?
Seven days gives you your real number. A month of three-pocket weeks gives you the first Reserve and the first steady Wage.
Resources to Fill the Three Pockets
| Resource | What it does for The Move |
|---|---|
| A plain notebook | Steps 1 and 2. Seven days of cash in and out, written by hand. |
| Three envelopes or tins | Gives Stock, Wage, and Reserve a physical home before you have an account for each. |
| A separate account or savings pocket | Keeps the business money away from the card you use for groceries. |
| Your existing stokvel, if you’re in one | Proof that you already stick to a structured contribution. Use that same discipline for the Reserve. |
| Free R500 Startup Guide | For when the squeeze is that not enough comes in. Five low-cost business ideas to build income that is yours to budget. |
Name Your Pockets With Us
Your hustle already works. The hours are there.
This week, find your real number. Seven days, one notebook, three pockets.
Then join the WhatsApp channel, where Week 6 lands next Monday and where we work through these moves together. Link at the top of the page.
Money You Didn’t Learn At Home Series:
- The Money Rules Nobody Taught You
- Payday Is a Mirror, Not a Moment
- The Silent Contract: Black Tax and the Money You Don’t Get to Keep
- Why You Spend Fast, Freeze Up, or Hide It
- Your Hustle Is a Business—Start Treating It Like One—You Are Here